Commercial Analysis
Sep 24, 2026 10 min read

Dubai Office Market: Rents, Prices & Supply

Dubai's office market is the one part of this property market that is still tightening, and it is described in public by five research houses who do not agree with each other. CBRE and JLL put different numbers on the same quarter's prime rents. Savills and Knight Frank differ six-fold on how much new space is coming. What follows is what is measured, who measured it, over what period — and where the disagreements are, because a number quoted without its source is how a market gets misread.

Dubai Office Market: Rents, Prices & Supply

Two things are true about Dubai property in 2026 and they point in opposite directions. Office rents rose 13% year on year in Q2 2026, prime offices 16%, with occupancy around 94%. In the same quarter and the same report, residential rents fell 2.6% year on year and 6.2% quarter on quarter (CBRE, UAE Real Estate Market Review Q2 2026). A market commentary that describes Dubai as uniformly hot, or uniformly cooling, is describing something that does not exist.

The figures below cover rents, vacancy, prices, supply and tenant size, each with the house that published it and the period it covers — including the places where two reputable houses disagree, which is more often than the headlines suggest.

At a glance

The six numbers this market is described by

  1. 01 Office rents Q2 2026 against Q2 2025 — rental growth, not an investor's yield +13% CBRE Q2 2026, prime +16%
  2. 02 Vacancy Lowest in more than a decade, with Grade C still the loosest grade 6.1% JLL Q2 2026, 7.7% a year earlier
  3. 03 Average asking rent Flat quarter on quarter — the first since H1 2021 AED 238/ft² Savills Q2 2026, per year
  4. 04 Ready office price DLD registrations, 1 January – 19 May 2026 AED 2,266/ft² off-plan the same period: 4,349
  5. 05 Office sales 2025 Best year in eleven, and the reason every developer now has an office product AED 13.1bn Cavendish Maxwell, +102% on 2024
  6. 06 Who the tenant is An SME, a start-up, or a company that has just moved to the UAE 66% of leases under 500 ft², Savills Q2 2026
1

Rents: up, but the number depends on who is measuring and against what

CBRE, Q2 2026 against Q2 2025: average office rents +13%, prime +16%. JLL, the same quarter, same basis: Grade A +26.2%, Grade B +31.5%, prime +13.6%. Those two prime figures — 16% and 13.6% — describe one quarter and do not reconcile, so each belongs beside the name of the house that published it, and neither belongs in an average.

A third measurement adds the part that matters most for timing. Savills, Dubai Office Market Report Q2 2026: the average asking rate stood at AED 238 per ft² per year with no quarter-on-quarter growth — the first such quarter since H1 2021. Read together, the three say: still sharply up against last year, flat against last quarter. Both are true and they use different bases. Quoting the year-on-year figure while implying the market is still climbing week to week is the most common error in this market's coverage.

For the longer arc: city office rents rose 22.4% in H1 2024 (Knight Frank), 22.9% across 2025 (Cavendish Maxwell) and roughly 14% in Q1 2026 (ZāZen Properties). By district, Knight Frank measured DIFC at AED 355/ft² and the Trade Centre District at AED 350/ft² in mid-2024, with Za'abeel around AED 550/ft² in 2025–2026 — the most expensive addresses in the city.

The caveat that has to travel with all of it: rental growth is not an investor's return. A yield also depends on what you paid, what stands empty, what the service charge takes and what the fit-out costs. Section 3 deals with the price side, and the next piece in this series deals with the net return.

Overall office rents
+13% y/y
Prime offices
+16% y/y
Market average
AED 238/ft²/yr
2

Vacancy: the lowest in more than a decade, and still not zero

JLL, Q2 2026: citywide office vacancy 6.1%, against 7.7% a year earlier. By grade: Grade B 8.0% (was 10.9%) and Grade C 10.9% (was 12.7%). CBRE, Q2 2026: occupancy ≈94%, which it attributes to the continuing shortage of Grade A stock; prime buildings in central locations were above 95% in early 2026.

The correct sentence is that office vacancy is at its lowest level in more than a decade. Two sentences that are not correct, and that appear constantly: «there is no vacancy» — 6.1% is not zero, and Grade C still holds 10.9%; and «the tightest market in the region» — in the same JLL quarter Abu Dhabi recorded 1.4% vacancy with prime availability at 0.1%. Dubai is tight. Abu Dhabi is tighter.

Leasing activity confirms the direction: lease registrations rose 24.6% year on year and 15.1% quarter on quarter in Q2 2026 (JLL), and Savills counted 38,082 office leases in the quarter on DLD data — 27,121 new and 10,961 renewals.

City vacancy
6.1%
Grade B vacancy
8.0%
Occupancy
≈94%
3

Prices: an office costs what a home costs, and twice that in Downtown

This is the section that most often surprises a buyer arriving from the residential side. Cavendish Maxwell, full-year 2025: the average office sale price reached AED 1,951/ft², up 25.9%. Betterhomes on Property Monitor data, July 2025: the average residential price was AED 1,893/ft². Per square foot, the two are within 3% of each other. In Downtown the office is twice the home: AED 5,130/ft² for offices, up 29% year on year (Knight Frank, 2025), against AED 2,504/ft² residential (Chestertons Mena, August 2025).

The transaction record sharpens it further. On DLD registrations for 1 January – 19 May 2026, ready offices averaged AED 2,266/ft² (AED 1,964 across 2025) and off-plan offices averaged AED 4,349/ft² (AED 2,388 across 2025) — analysis of DLD registrations published by Gulf Business on 21 May 2026. By district, ready deals ran at AED 2,517/ft² in Business Bay and AED 2,050/ft² in JLT. The average office ticket rose to AED 6.41M from AED 3.0M.

An office is not a cheaper way into Dubai property. It is a different income profile, and that is a different proposition.

Volume, for scale: AED 13.1bn of office sales across 2025 on about 4,600 deals, up 102% in value and 53% in count — the strongest year in eleven (Cavendish Maxwell). Business Bay and JLT led on deal count with 1,230 and 1,067 respectively, ahead of Barsha Heights (267), Dubai Silicon Oasis (147) and Dubai Investments Park (92). Knight Frank separately counted 167 office deals above AED 10M in 2025, up 114% on 2024.

Office, city average
AED 1,951/ft²
Residential, city average
AED 1,893/ft²
Office, Downtown
AED 5,130/ft²
Lumena
Business Bay

Lumena

A launch price and a buyable price are two different numbers here. Omniyat's AED 19M is still printed on its own project site directly above the words «officially sold out» — nobody can transact at it. The buyable entry is the resale floor: the lowest of twelve live Property Finder listings, 13 August 2026.

AED 25.1M resale asking, Aug 2026
50/50 payment plan
Q4 2029 handover
View Project →
More about Lumena
4

Supply: the published forecasts disagree by a factor of six

Total Dubai office stock is 100.6M ft² (JLL, Q2 2026). What arrives next is where the public record breaks down, and the spread itself is the finding:

  • Savills, Q2 2026: ≈1.9M ft² completing in 2026, pipeline above 4.2M ft² to 2030.
  • JLL, Q2 2026: ≈940,000 ft² completing by the end of 2026.
  • Knight Frank, 2026 forecast: 24.2M ft² across 2026–2030, concentrated in Business Bay, Meydan City, JLT and DIFC, with DIFC alone at 7.7M ft² to 2040.
  • Cushman & Wakefield Core / JLL: 0.89M ft² delivered in 2025, 6.4M ft² in development for 2026–2027.

Savills' «above 4.2M ft² to 2030» and Knight Frank's «24.2M ft² in 2026–2030» are not a rounding difference; they are almost certainly counting different things — one grade, one geography, one definition of «pipeline» against another. No published methodology reconciles them, so a supply figure is usable only with its author's name attached.

What every house does agree on is that the new space is committed before it opens. DIFC Square, one of the few large Grade A completions of the year, was substantially pre-let before construction finished; Immersive Tower, due July 2027, already had significant space under offer in Q2 2026; and Savills states plainly that most future Grade A supply will be pre-leased or absorbed by existing demand, limiting its effect on the market. CBRE records the same mechanism in DIFC, TECOM and DMCC. CBRE's head of MENA research, Taimur Khan, described the market in early 2026 as being in one of the tightest supply situations in its modern history.

That is the structural reason the off-plan office exists as a product at all: buyers who cannot find finished space buy an unfinished building instead. The fourth piece in this series takes that trade apart.

Total office stock
100.6M ft²
Completing in 2026
≈1.9M ft²
JLL, same year
≈940,000 ft²
Eaton Square
Meydan Horizon, MBR City

Eaton Square

A full-floor, one-tenant-per-floor product landing into the 2026–2028 window — a building of this size trading on broker asking prices, with its developer attributed differently by different portals.

AED 42M full floor, broker asking Sep 2026
70/30 payment plan
Q2 2028 handover
View Project →
More about Eaton Square
5

The tenant is smaller than the brochures imply

If you are buying an office to let, this is the number that matters most. Savills on DLD data, Q2 2026: deals under 500 ft² accounted for 66% of all office leasing, up 17% quarter on quarter. ZāZen Properties, Q1 2026: roughly 97% of office transactions involved space under 3,000 ft². Demand by sector, H2 2025: banking and finance 32.5%, technology 23.1% of new office requirements — together more than half (Knight Frank).

The Dubai office buyer is letting a small suite to an SME, a start-up or a company that has just moved to the UAE, not a floor plate to a multinational — and the registration data supports that reading: Dubai Chamber of Commerce recorded 71,830 new member companies in 2025, taking the total to 292,486, up 13.2% (Cavendish Maxwell / Dubai Chamber). Which is precisely why an office product that starts at 596 ft² is a serious product and a product that starts at a whole floor is a different business.

Leases under 500 ft²
66%
Deals under 3,000 ft²
≈97%
Office leases, Q2 2026
38,082
Haus of Tenet
Business Bay

Haus of Tenet

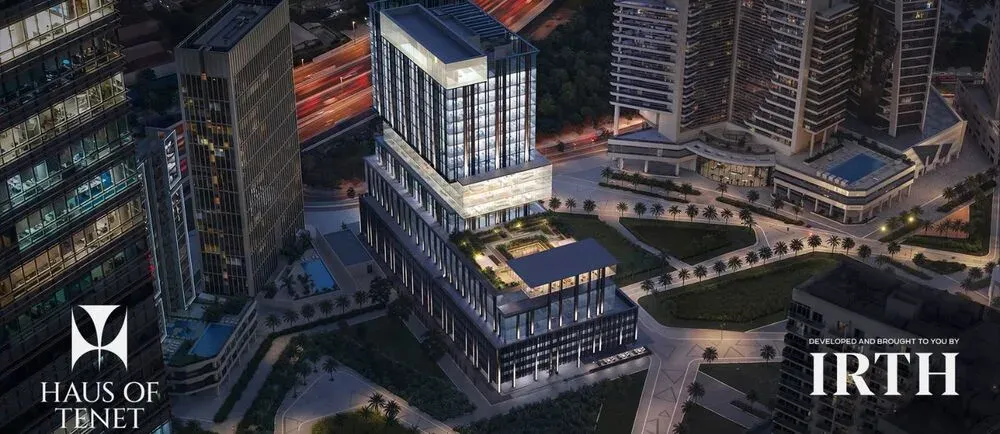
Built for the tenant the data actually describes: Classic suites run from 596 ft², which is inside the 500–3,000 ft² band that accounts for almost every lease signed in Dubai. Entry price unanimous across IRTH's own material and six independent channels, checked June 2026.

AED 3.2M Classic suite from, Jun 2026
10/40/50 payment plan
Q2 2028 handover
View Project →
More about Haus of Tenet
6

What these numbers do not tell you

Four limits that change how the figures above should be used.

  • No institutional cap rate exists in public. None of the five houses — CBRE, JLL, Knight Frank, Savills, Cavendish Maxwell — publishes a net yield or cap rate for Dubai offices in an openly available document. Every office yield figure in circulation, the ones in the next piece included, is a broker estimate and should be read as one.
  • The averages hide the concentration. Off-plan office sales in H1 2026 reached AED 13.1bn across 1,668 units — more than the previous seven years combined (2019–2025: AED 5.48bn on 1,821 deals), per an analysis of DLD data by Al Masdar Al Aqaari published 2 July 2026. But five projects accounted for 71.7% of that value and 51.3% of the deals: Lumena and Lumena Alta (Omniyat), AHS Tower, Shahrukhz (Danube) and 31 Above (Beyond) — 856 deals and over AED 9.4bn between them. Lumena, Lumena Alta and AHS Tower each have their own page in this section. A handful of towers carried the off-plan office market through that half-year.
  • Two different «AED 13.1bn» figures are in circulation and they are not the same measurement. Cavendish Maxwell's AED 13.1bn is all office sales across full-year 2025. Al Masdar Al Aqaari's AED 13.1bn is off-plan only across H1 2026. The same house gives 2025 off-plan offices as AED 4.6bn. The coincidence is striking, and the two never belong in one sentence without their metrics spelled out.
  • Liquidity is thin by residential standards. About 4,600 office transactions in a record year, against tens of thousands of apartment sales. That affects how quickly you exit and how confidently anyone can value what you own.

The complete CBRE, Savills, Knight Frank and Cavendish Maxwell PDFs sit behind access controls, so most figures above come from press releases and press coverage. Ask us for the primary document on any number that has to carry weight in your offer.

Read next: Commercial vs Residential: What Changes the Net Return — why the yield gap is real in the secondary and value-add segment and absent in prime, what VAT does to a commercial purchase that it does not do to a home, and which costs come off the rent before you see it. Or go back to the commercial section for the buildings themselves.

Related guide: Dubai Commercial Property Investment Guide — the umbrella piece that puts these measurements next to the buying mechanics, the two buyer routes and the twenty buildings.

More commercial analysis

Get the Brochure

We'll send it to your WhatsApp shortly.